
Artrya fell -21% last week and at one point, was down another -8% today. At today’s close, the shares are down -50% from their all-time high of $6.49 set just three months ago on the 6th July. The pullback is partly a result of disappointing 4Q26 results (see ‘Valuation downgrade but market overreaction is a buying opportunity’) compounded by 1) last Tuesday’s rejection by the FDA of EchoIQ’s EchoSolv HF submission; and 2) the ongoing delay in Salix Coronary Flow FDA submission.
On Tuesday after market close EchoIQ (ASX:EIQ) announced that its EchoSolv HF product had failed to achieve FDA clearance. The FDA issued a Not Substantially Equivalent (NSE) determination, meaning EIQ’s attempted use of the 510(k) equivalence pathway was invalid. EIQ management is reviewing the determination but did not provide details of the expected path forward.
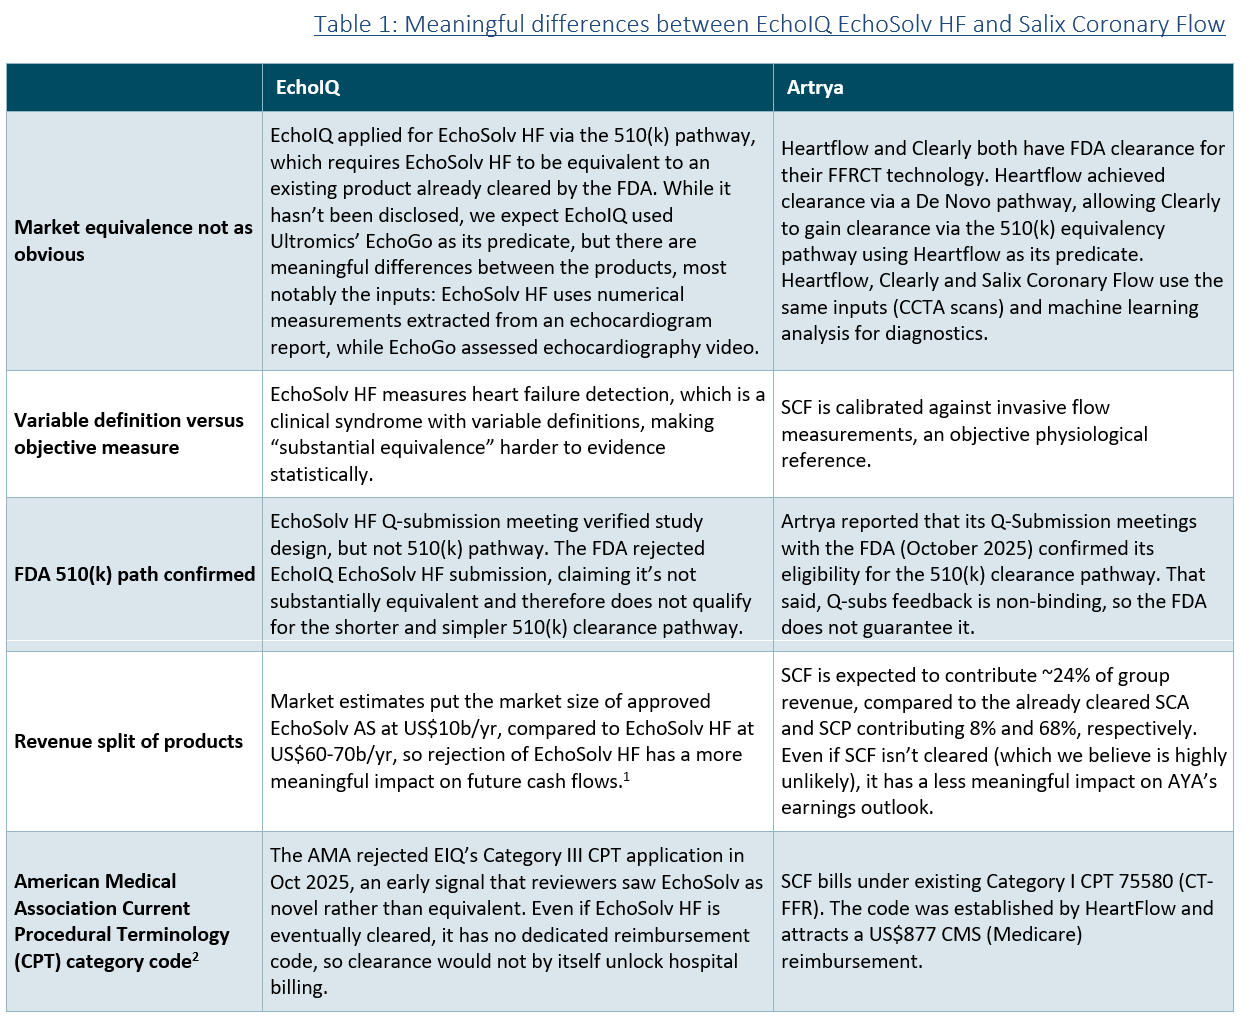
The market interpreted this ruling as a potential risk to AYA’s own Salix Coronary Flow application (not yet submitted), resulting in the drop in share price. We argue that sufficient differences between EchoSolv HF and SCF render the comparison largely meaningless.
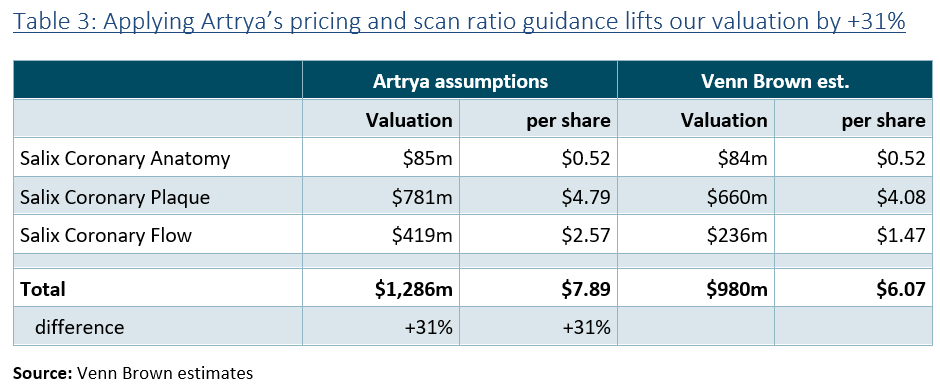
After Artrya reported its fourth-quarter results, we significantly pushed out our expectations timing of cash flows. We extended the buffers between our forecasts and management guidance, resulting in +31% upside if results more closely resemble guidance rather than our estimates.
On 4th September, S&P/ASX announced Atrya would join the S&P/ASX 300 index. We estimate AYA will represent around 2.7 basis points of the index, requiring passive index-tracking funds to acquire ~10 million shares, or approximately 14 days of average trading volume.
We maintain our $6.07 valuation. Recent extraneous market events have compounded negative sentiment around Artrya and created a compelling buying opportunity. We believe the market will need visible evidence of market traction before fully rallying behind the stock.
Catalysts remain: SCF FDA submission, commercialising SAPPHIRE partners, SCF FDA clearance, delivery of meaningful customer revenue.