
Artrya announced on Friday that it had signed a five-year commercial agreement with SAPPHIRE partner Huntsville Hospital Health System. Huntsville is the first SAPPHIRE partner to sign a commercial agreement. The market responded positively, with the stock trading as high as $4.20 (+22%) before closing at $3.70 (+7.9%).
We have been firm supporters of Artrya’s marketing strategy of working with key thought and industry leaders to build credibility and visibility, giving them access to senior hospital system decision-makers rather than using the traditional approach of having an army of expensive salespeople walking the streets trying to gain entry from the bottom up. It’s encouraging to see this approach paying dividends.
The Huntsfield contract is the fourth commercial contract AYA has signed, and like the others, it appears to consist of a fixed monthly fee with no volume component for Salix Coronary Anatomy scans. This is a departure from the ~US$50 per scan guidance previously provided.
Contract Details
It remains unclear whether this is a permanent change to the pricing model or simply a decision to remove friction from the early adoption sales process. Regardless, it seems unlikely that AYA can negotiate meaningfully better (or per-scan) terms with the remaining five SAPPHIRE partners, so at least in the short and medium term we don’t expect per-scan pricing for Salix Coronary Anatomy. We might get some clarity on this point from management during the conference call.
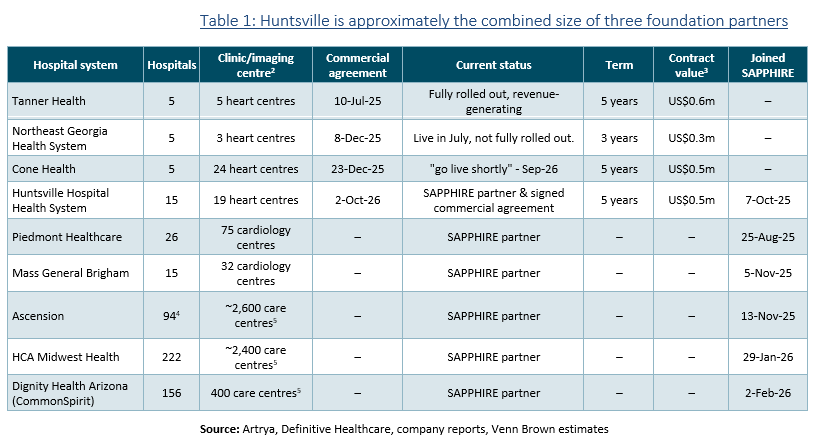
We don’t see the removal of SCA per-scan fees as a poor outcome. Anything that gets Salix into more hospitals faster is a good thing. We’ve long seen Artrya’s market entry as a land grab. Assuming Salix delivers the workflow and diagnostic benefits that management and existing customers report, once installed, it will be difficult to displace, and if removing the SCA fee accelerates this, then we see it as a positive move.
Artrya are holding a conference call to provide more details on the deal and answer investor questions:
Following AYA’s FY26 results, we pushed out our cash flow expectations. Our modelling assumes revenue from SAPPHIRE partners does not materialise until 2Q28 (Dec-27). Any shortening of this period is positive, albeit we have not yet removed the SCA scan fee from our figures, which accounts for roughly 9% of our expected revenue.
We maintain our $6.07 valuation. Recent extraneous market events have compounded negative sentiment around Artrya and created a compelling buying opportunity. We believe the market will need visible evidence of traction before fully rallying behind the stock. Catalysts remain: SCF FDA submission, commercialising SAPPHIRE partners, SCF FDA clearance, delivery of meaningful customer revenue.
Download the full report below.